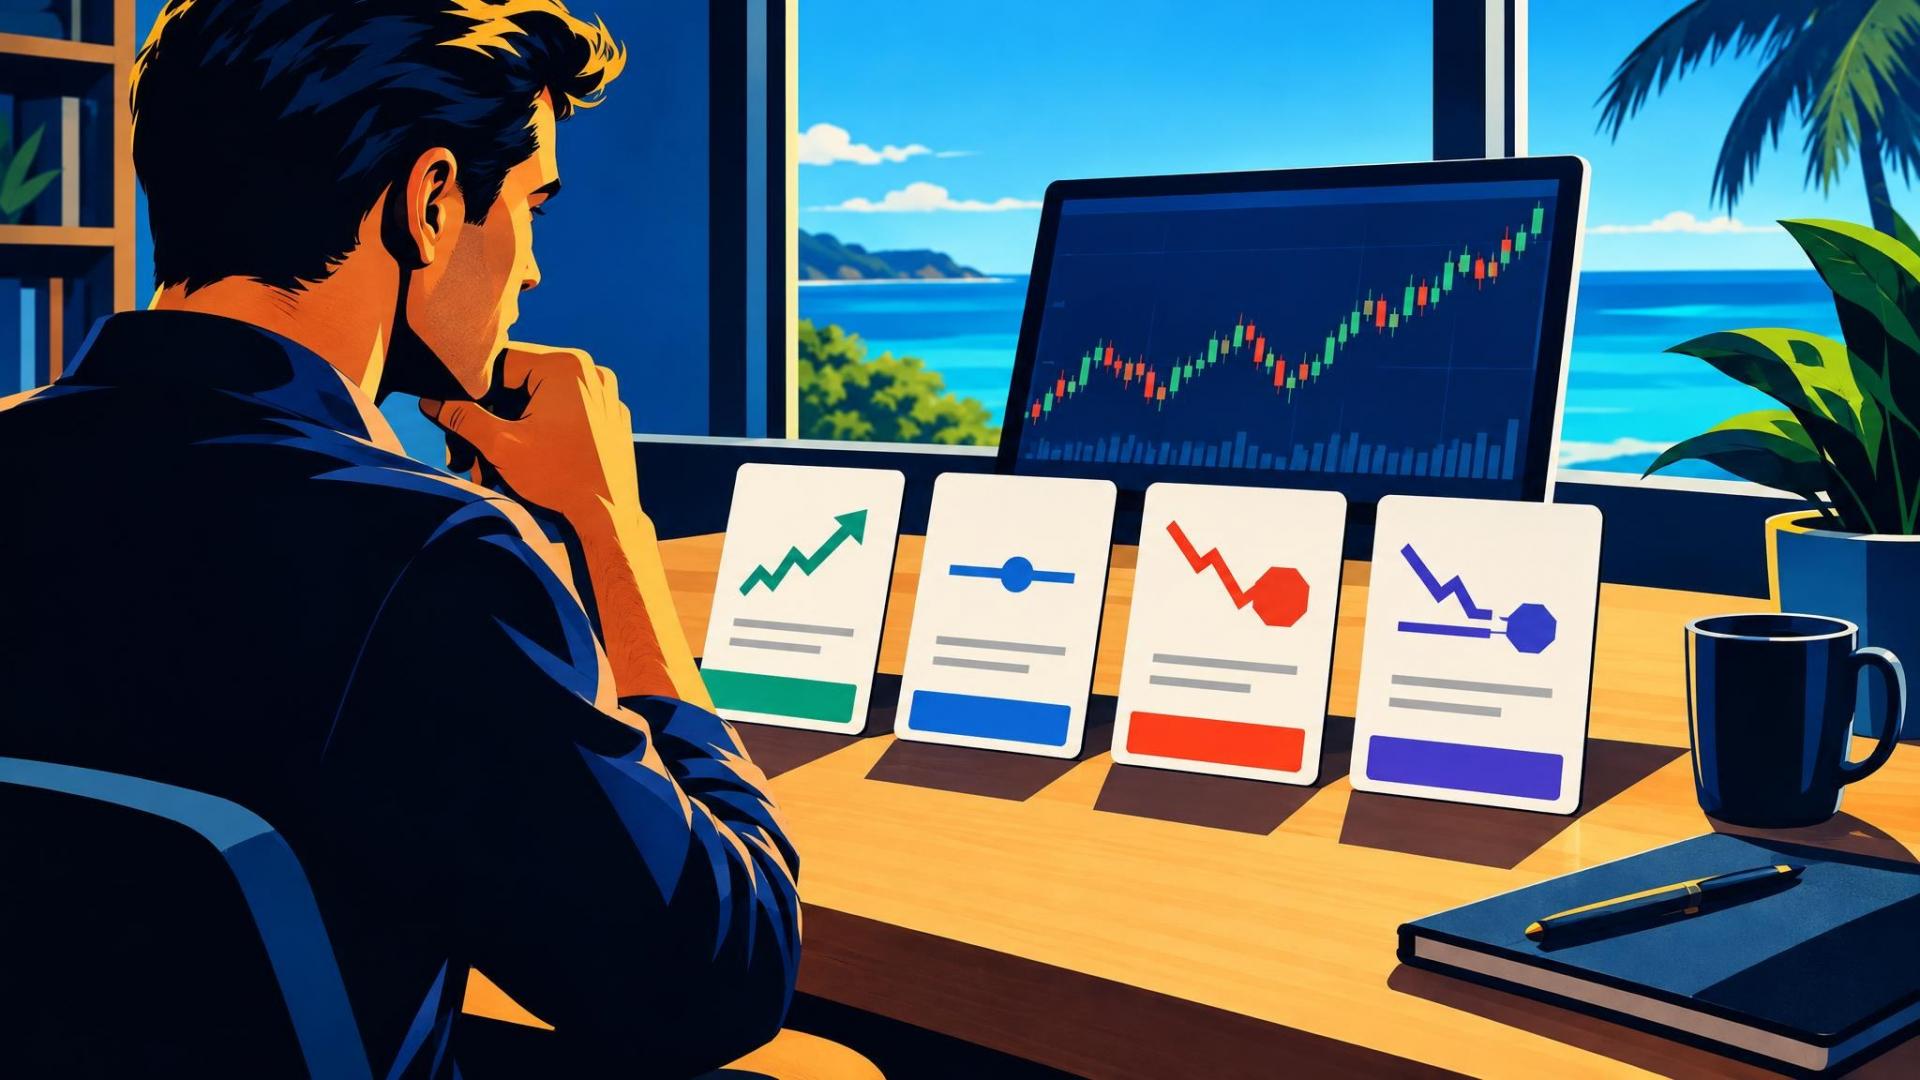
The order button is not just a button. Before a broker can buy or sell a security, it needs to know which problem matters more to you: getting the trade done promptly, controlling the price, or waiting for a price threshold. Market, limit, stop, and stop-limit orders express different answers.
Understanding that distinction can prevent a surprisingly common mistake: assuming that a price displayed on a screen is the price you will necessarily receive.
Start with the basic trade-off
Most order types involve a choice between execution certainty and price certainty.
- A market order prioritizes execution. You are asking to trade as soon as possible at the best price currently available.
- A limit order prioritizes price. You set the worst price you will accept, knowing the trade may not happen.
- A stop order waits for a trigger price, then becomes a market order.
- A stop-limit order waits for a trigger price, then becomes a limit order.
None removes investment risk. Each simply gives the broker a different instruction about how to handle price and timing.
Market orders: “Execute now at the available price”
A market order tells the broker to buy or sell promptly at the best available price. It is usually the straightforward choice when a security is liquid and completing the trade matters more than obtaining one exact price.
The catch is that “market price” is not a guaranteed number. In a fast-moving market, the price can change between the quote you see and the moment the order reaches available buyers or sellers. This difference is often called slippage.
For a thinly traded security or during sharp volatility, that difference can be material. A market order usually offers the strongest likelihood of execution, not a promise that it will fill at the last price displayed on your screen.
Limit orders: “Trade only at this price or better”
A limit order sets a boundary. With a buy limit, you name the most you are willing to pay. With a sell limit, you name the least you are willing to accept.
Suppose a share is quoted around $50. A buy limit at $48 says: buy only if shares can be obtained for $48 or less. If the price never reaches that level while the order is active, no purchase occurs. A sell limit at $55 works in the other direction: sell only at $55 or more.
That is the central limit-order bargain: you control the acceptable price, but you give up certainty that the trade will be completed. A limit order can also receive only a partial fill if there are not enough shares available at your chosen price.
Stop orders: a trigger, not a guaranteed exit price
A stop order becomes active when the security reaches a specified stop price. A sell stop is commonly placed below the current market price; once triggered, it becomes a market order to sell. A buy stop is commonly placed above the current market price; once triggered, it becomes a market order to buy.
The important point is easy to miss: the stop price is a trigger, not the price you are guaranteed to receive. If a sell stop at $45 is triggered during a rapid decline, the resulting market order may execute below $45. A brief intraday move can also trigger an order even if the security later recovers.
Brokerage firms may differ in the stop orders they offer and in how they determine whether a stop price has been reached. Before relying on one, read your broker’s order-ticket definitions and execution policy.
Stop-limit orders: more price control, less certainty of execution
A stop-limit order uses two prices. The stop price activates the order; the limit price sets the boundary for execution after activation.
For example, an investor holding a share near $50 might enter a sell stop-limit order with a stop at $45 and a limit at $44. Once the price reaches $45, the order becomes a limit order to sell at $44 or better. If the market falls quickly through $44, however, the order may remain unfilled while the position continues to lose value.
So a stop-limit order addresses one risk of an ordinary stop order—the possibility of an unexpectedly poor execution price—but introduces another: no execution at all.
Check the order’s lifetime as well as its price
Order instructions also include a time condition. A day order normally expires at the end of that trading day if it has not been executed. A good ’til canceled order can remain active longer, subject to the broker’s own maximum duration and cancellation rules.
Extended-hours trading deserves extra care. Trading can be thinner outside regular market hours, and brokers often restrict which order types they accept. An order that makes sense during the regular session may behave differently when fewer buyers and sellers are participating.
A quick pre-submission check
- Name the priority. Is prompt execution more important, or is a specific price more important?
- Read the full order ticket. Confirm whether you selected market, limit, stop, or stop-limit—and whether the order is to buy or sell.
- Check every number. A stop price and a limit price serve different functions; reversing or mistyping them can change the instruction completely.
- Check the duration and session. Know whether the order is day-only, remains open, or applies in extended hours.
- Review your broker’s rules. Available order types, triggering methods, fees, and handling can vary by firm and by security.
Order terminology is worth learning because it turns a vague intention—“sell if this gets too low” or “buy if it comes down”—into a precise instruction with real consequences. For a compact plain-English reference to the vocabulary behind orders, funds, risk, valuation, and markets, The Investing Dictionary is designed to help readers look up an unfamiliar term and return to the decision at hand with a clearer understanding.
This article is general educational information, not individualized investment advice. A particular order type can carry different risks depending on the security, market conditions, account type, and brokerage firm.